Saturday, January 31, 2015

One Decade Down, Next to Go

It is humbling to consider that today marks our 10th Blogiversary. Well over 7,000 posts and millions of views, numerous awards and links from the New York Times, Wall Street Journal, Forbes, Fox and others.

And, of course, the very best co-bloggers on the 'net.

But most important: our terrific, engaging and interested readers.

Thank you all for 10 great years - and now on to 20!

Friday, January 30, 2015

And speaking of Medicaid...

As Bob recently noted, Indiana has become the 28th state to climb on board the  Medicaid expansion train (wreck). He also pointed out that there's already a shortage of providers willing to take on Medicaid patients.

Wonder why?

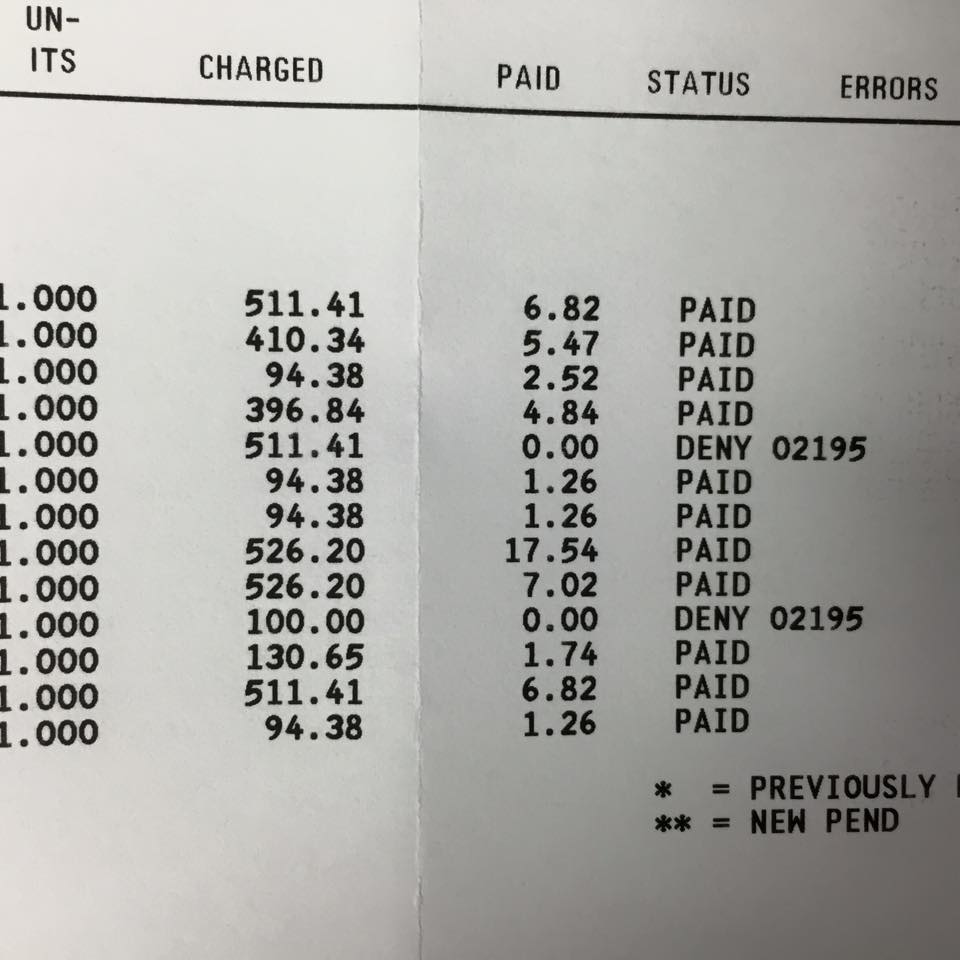
Well, our friend Dr Val has a pretty graphic answer:


Click on over to read the whole story (and definitely check out the comments).

Another Installment of: That's NOT how it works

It seems like only a  week ago that we referenced our 2nd ever post - wait, it was a week ago that we did that! And here we are again, talking about insurance fraud. And this one's a doozy:

"Irina Vorotinov has been charged by ... with defrauding Mutual of Omaha Insurance Company of more than $2 million in life insurance proceeds by falsely claiming that her former husband had died."

Turns out - Spoiler Alert! - the ex- was, in fact, very much alive, and caught on film years after his alleged death.

Ooops.

Thursday, January 29, 2015

Super(bowl) Health Wonk Review is up

Our favorite health care economist, Jason Shafrin, hosts this week's festive round-up of health care policy and polity. It's cold outside, so come in and warm up with some great reads.

Wednesday, January 28, 2015

Some thoughts on subsidies

So, been having a bit of a Twitter-tussle with a well-regarded friend and colleague. At issue is the future of ObamaTax subsidies as we look forward to the resolution of Burwell/King/Halbig.

Which got me to thinking: Why we're having this discussion at all? After all, President Obama explicitly promised us that, under the ObamaTax, premiums would decrease 3000%, and that we would have comprehensive, affordable coverage.

If this were truly the case, then why would we need bribes subsidies in the first place? After all, who wouldn't want cheap, useful insurance coverage? Why would we need to be cajoled, nay, forced into buying it if it was such a great bargain?

And if, as Mike pointed out years ago, the folks in DC actually did their jobs, would we need to be expanding Medicaid?

Thought not.

Tuesday, January 27, 2015

Tuesday Spindle-clearing

In no particular order:

■ Coming as a surprise to no one who's been paying attention:

"A quarter of firms that that had offered insurance to their employees last year were canceling their health plans this year, and another 25% said they planned to do so next year."

This in Michigan, and focused on smaller companies not (yet) subject to the Employer Mandate. Talk about blizzards...


■ Could treating Alzheimer's really be this simple?

"Researchers say they’ve developed a nasal spray that could potentially improve memory and other mental capabilities for the more than 5 million Americans suffering from Alzheimer’s disease."

It's still a long way off (and currently being tested only on those with mild cases), but sounds promising.


■ Almost 5 years ago, we wrote about a "Lifespan Calculator:" an online widget that purported to predict how many days one had left. It appears that the technology is improving:

"A test to determine if elderly patients will die within 30 days of being admitted to hospital has been developed by doctors to give them the chance to go home or say goodbye to loved ones."

Corrected for accuracy:

"A test to determine if elderly patients will die within 30 days of being admitted to hospital has been developed by doctors to encourage them onto the Liverpool Pathway."

There, better.


■ But hey, "middle class:"

"I’m sorry sir,” the polite Healthcare.gov customer-service agent said. “There’s nothing I can do. You’re either going to have to enroll in Medicaid or you’re going to have to pay the full health-insurance rate.”

The problem, of course, is that the gentleman in question had the misfortune to fall within the one category for which the ObamaTax was supposed to work, but never quite has. As a grad student, he wasn't worried about his next BMW, but neither was he worried about his next meal. Couple that with the problem that, if one is eligible for Medicaid one is not eligible for a subsidy, and one begins to see the problem.

I really like the author's take on this, by the way: "Call me crazy, but in my book Medicaid is a last resort, not a first option."

It's so easy to forget that this is no game, no theory; it hurts real people, every day.

DC's Best Kept Secret

What with all the reports of how well Open Enrollment v2.0 has been going, it's no wonder the folks in charge want to keep this under wraps:

"It will cost the federal government – taxpayers, that is – $50,000 for every person who gets health insurance under the Obamacare law"

But that's only the tip of the proverbial iceberg:

"It will take $1.993 trillion, a number that looks like $1,993,000,000,000, to provide insurance subsidies ... and to pay for a massive expansion of Medicaid and CHIP"

But hey, worth it to provide universal health insurance coverage.

Wait, what?

"The best-case scenario described by the CBO would result in 'between 24 million and 27 million' fewer Americans being uninsured in 2025, compared to the year before the Affordable Care Act took effect."

So after 15 years and $1,993,000,000,000, they still won't have everyone covered?

Gee, sure glad they passed it to find out...

(And notice, one has to go to the UK press to find this)

Monday, January 26, 2015

CoOpportunity assumes room temp

Last month, we reported on the travails of Iowa's CoOpportunity Health, a start-up recently taken over by Hawkeye State regulators. FoIB Josh Archambault tips us that they've now been shuttered:

"Iowa’s insurance regulator plans to shut down insurer CoOportunity Health, marking the first failure of one of the nonprofit cooperatives created under the Affordable Care Act."

T'won't be the last.

Saturday, January 24, 2015

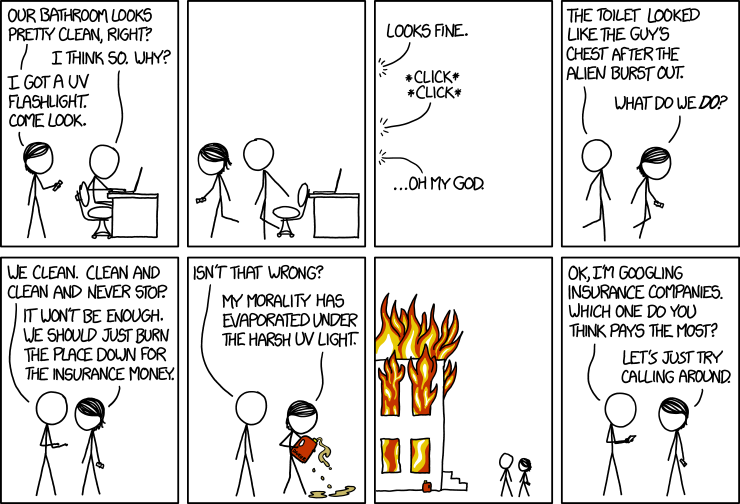
P&C Files: That's *NOT* How It Works!

[click pic to embiggen]

[Hat Tip: DoIB Sarah S]

Friday, January 23, 2015

Flashback Friday

Our 2nd ever post here was a recap of the "Top Insurance Swindlers" of Ought-four. It was a rogues gallery that included a "greedy granny" and an arsonist pastor, among others (no mention of the apocryphal cigar owner). In fact, you'll notice an edit dated earlier this month: a business owner had emailed me requesting that I modify an entry because - ten years on - it was adversely affecting her business.

Fast forward a decade, and we have the truly inspirational story of an entire family of (alleged) insurance fraudsters:

"Authorities said the ensuing probe uncovered a decades-long pattern of questionable insurance claims ... Six other people, including her husband, two children and daughter-in-law, also face charges."

Bet Thanksgiving dinner is a hoot.

Thursday, January 22, 2015

Medicaid and Long Term Care

Many folks continue to believe - erroneously - that Medicare will cover most (if not all) of their long term care needs. It won't. But Medicaid probably will, if you lack the assets to self-pay.

Unfortunately, this requires that one "spend down" one's assets, accumulated over a lifetime of toil. To qualify for assistance from Medicaid to cover long term care expenses, one is allowed to keep only a small amount of cash, a home and a car, maybe a few baubles.

The good news is that buying a Partnership-qualified long term care insurance plan, one may offset some of that spend down, and keep more assets.

And, as local ElderCare Law guru Michael Millonig informs us via email this morning:

"Level of Assets That Spouses of Medicaid Recipients May Keep Rises for 2015 ... [For example] If a couple has $100,000 in countable assets on the date the applicant enters a nursing home, he or she will be eligible for Medicaid once the couple's assets have been reduced to a combined figure of $52,000 -- $2,000 for the applicant and $50,000 for the community spouse."

Click on through for more details.

Wednesday, January 21, 2015

Is Healthcare.gov really just a massive voter data collection tool for DNC? [UPDATED]

[Scroll down for update]

Seeing how Obama has abused the IRS and voter registration this isn't such a stretch:
"Daoudi's company — Catchpoint Systems— came across some 50 third-party connections embedded on HealthCare.gov. They attracted attention because such connections can slow down websites. They work in the background, unseen to most consumers.
The AP was able to replicate the results. In one 10-minute visit to HealthCare.gov recently, dozens of websites were accessed behind the scenes. They included Google's data-analytics service, Twitter, Facebook and a host of online advertising providers."
A list of 9 million potential voters who "benefited" from government largess along with their facebook and twitter friends would be very valuable come Get Out the Vote time.  

UPDATE [HGS @ 1/21/15]: And it gets worse:

"... healthcare.gov – the flagship site of the Affordable Care Act, where millions of Americans have signed up to receive health care–is quietly sending personal health information to a number of third party websites."

Including Doubleclick.net, Twitter and even Youtube.

Hey, if you like your privacy, you can keep....

A Giveaway is Now a Threat

As open enrollment creeps across the finish line in year two, many organizations that support Obamacare are changing their marketing plans. The first year and the opening of this year focused on the ever popular "giveaway" model. It came in two parts.

1. Give people something for free. From free birth control to free preventive care people should sign up for health insurance because these benefits wouldn't cost anything. Never mind the fact that doctors and pharmacies aren't really giving this stuff away.

2. Explain that Government thinks this is important for you to have insurance so they are paying the majority of your premiums. Never mind the fact that if your income is above $20,000 to purchase a Silver Level plan you will pay 5% of your income for it. Never mind the fact that cheap insurance means high out-of-pocket costs for health care.

Now comes the third marketing campaign:  Explain the consequences of not buying insurance. The dreaded and unpopular individual mandate and the tax you have to pay for not buying government approved health insurance with free stuff in it. Never mind the fact that you are being taxed to help pay for parts one and two above.

Yep, that should do the trick.

Tuesday, January 20, 2015

Everything Old is New (Again)

Way back in the early days of this blog, we reported on a seasoned citizen who chose a life at sea as her Long Term Care plan:

"On our October cruise on Royal Caribbean lines, there was an elderly lady who actually resided on the ship 'Voyager of the Sea ... She told us that it was just more financially feasible to do this than living in an assisted-living home and was much more fun"

So it was with a sense of deja vu that I read this item this morning:

"Lee Wachtstetter, an 86-year-old Florida widow ... sold her five bedroom Fort Lauderdale area home on 10 acres and became a permanent luxury cruise ship resident ... has been living on the 1,070-passenger vessel longer than most of its 655 crew members — nearly seven years."

One interesting tidbit: in our original story, the traveling senior reported spending over $200,000 a year; by contrast, Mrs Wachtstetter seems to have scored quite the bargain at a little over $160,000 annually.

Sweet Sailing, Mama Lee!

Monday, January 19, 2015

Counting down the ObamaTax

As you've no doubt seen all over the news, once Open Enrollment v2.0 is over next month, folks who failed to take advantage of it and are still uninsured will (likely) be subject to a fine penalty tax. Many (most?) folks believe that the tax is a mere $95 this year and, for some people, this may well be the case. But it's actually just a minimum; the actual rate (this year) is 1% of income:

"TurboTax, an online tax service, estimated that the average penalty for lacking health insurance in 2014 will be $301."

On the one hand, that's a lot more than $95, but on the other, it's likely less than one month's premium, especially for folks who don't qualify for a subsidy.

Just for grins and giggles, I took an average person (age 35) living in the Mid-West and ran some quotes. I chose Anthem because, let's face it, Blue Cross is ubiquitous and, in many markets, the 800 lb gorilla. My hypothetical client, of course, eschews tobacco.

The least expensive plan available cost $253, and includes a maximum potential out-of-pocket (MOOP) liability of an additional $6,400 if he has a bad year. But assuming that, like most folks, his expenses are generally a flu shot and maybe a generic prescription (available for $4 at many retailers), this doesn't seem like such a good deal. It would take less than two months to be "in the hole" vice "going naked."

Now let's back up a bit and consider his younger brother, aged 28: he's eligible for a "Catastrophic" Plan (not to be confused with an HSA-compliant one), which comes with a MOOP of $6,600, and costs $180 per month. Again, a couple of months into it, and he's well past the $301 fine penalty tax, too.

Bottom line: why would anyone think that this is an efficient incentive?

Thursday, January 15, 2015

Health Wonk Review: Welcome to '15 edition now up

Vince Kuraitishos hosts this week's eclectic round-up of the first wonky blog posts of the New Year.

MVNHS© In The News

Since it's been a while since we've reported on the Much Vaunted National Health Service©, seems like it's a good time to catch up:

1 - Co-blogger Bob alerts us to this alarming news:

"More than 3,000 operations have been cancelled by the NHS in the first two weeks of [December] as an "unprecedented demand" takes its toll."

Here's the deal: When something is "free" (or, more precisely: perceived as free) then more folks are going to want it. After all, why would anyone in their right mind leave money (or health care) "on the table?"

It also points out that nationalized health care schemes do nothing to rein in demand, and by extension, cost.

2 - FoIB Peter K explains why the folks mentioned above may have been lucky to have been put off:

"A six-week-old baby was killed by her bipolar mother after she stuffed pages from the Bible into the infant's mouth, while supposedly in the care of bungling NHS staff."

What difference which book was used seems irrelevant and unhelpful; the important information here is that careless (overworked?) staff allowed such a person unfettered, unsupervised access to a vulnerable patient in their charge.

Could it happen here? Of course, but the difference is that this seems to be a pattern for MVNHS© folks:

"Other fatal errors by the Cambridgeshire and Peterborough NHS Trust included the shocking loss of records detailing an attempt by Lovemore in 2006 to smother her first child."

And that was just this one family.

Oy.

Wednesday, January 14, 2015

A Timely Reminder

Bob G vs "Survey Says!"

FoIB Bob Graboyes takes to the pages of US News to explain why judging the success (for certain values of "success") of the ObamaTax, based on ubiquitous and often self-selecting surveys, is destined to be disappointing:

"The phrasing of questions matters a great deal. Individuals surveyed may answer a pollster’s question dishonestly for a variety of reasons, or they may answer incorrectly because they don’t actually know whether they have qualifying insurance coverage."

Or maybe they think their better half took care of it. Doesn't really matter: you know the old saw about lies, damn lies and...

Bob wants to know just one simple thing: Why must we rely at all on these consumer surveys? They are subjective and prone to bias (both intentional and inadvertent). Surely there must be a better way?

And indeed there is. But you'll have to read his article to see what it is.

(It's worth it)

Tuesday, January 13, 2015

Bucks, Ducks and Luck

Congratulations to The Ohio State Buckeyes for their impressive route of the University of Oregon Ducks last night in Texas. While most of us here in Buckeye country are busy celebrating the win, one regional retailer is licking its wounds:

"Ohio-based Morris Furniture Company is now on the hook for upwards of $1.5 million in refunds to customers ... The promo promised refunds to customers who purchased at least $1,999 in furniture a ... if OSU won the championship game by at least seven points."

Which, by golly, they did.

So the chain is on the hook for an estimated $1.5 million dollars. That's the bad news. The good news is that they took a page from Chicago's World Furniture Mall, about which we wrote some 8 years ago:

"[The store] promised that if the Bears shut out the Packers in the season opener at Lambeau Field in Green Bay, Labor Day weekend shoppers would get their furniture free."

Which is what happened. Fortunately, the owner had purchased a "Special Event" policy for just such an occurrence, and was out only the price of the plan. So, too, the Ashley's folks "did work with a third-party company that underwrote the promotion."

Smart move.