Wednesday, November 29, 2017

Wrapping Up LTCi Awareness Month

As we near the end of LTCIAM, the good folks at Visionary Marketing offer this handy "Protection Decision Tree" to help folks determine what kind of plan might fit them best:
[click to embiggen]
 
Thanks, VMG!

Tuesday, November 28, 2017

ObamaCare Fail '17

Courtesy of FoIB Ʀєfùsєηíκ, the latest on this year's Open Debacle Enrollment:

"Obamacare Exchanges are on track to have 18-28% fewer members than at the end of last year's open enrollment."

Hardly surprising, of course, given the current state of premiums.

Here's another 1,000 words on the subject:

[click to embiggen]

#Winning!

[Chart courtesy of Forbes]

Monday, November 27, 2017

Much Vaunted National Health System© strikes again

Another day, another MVNHS© screw-up:

"A glamorous equestrian has been left in agony and vomiting her excrement after she claims minor keyhole surgery went horribly wrong"

34-year old Kelly Yeoman was initially hospitalized for a small "fluid filled sac" on her ovary. But by the time the (rocket?) surgeons were done with her, she was left confined to a hospital bed, her body "slowly filling with her own excrement."

And since it's not likely that her care's going to be getting any better under the auspices of the MVNHS©, her family and friends are trying to raise about $13,000 so she can avail herself of private treatment.

And it's urgent:

"[H]er bowel could perforate at any moment – at best meaning she would need a colostomy."

But hey, free!

A Tale of Two Scenarios

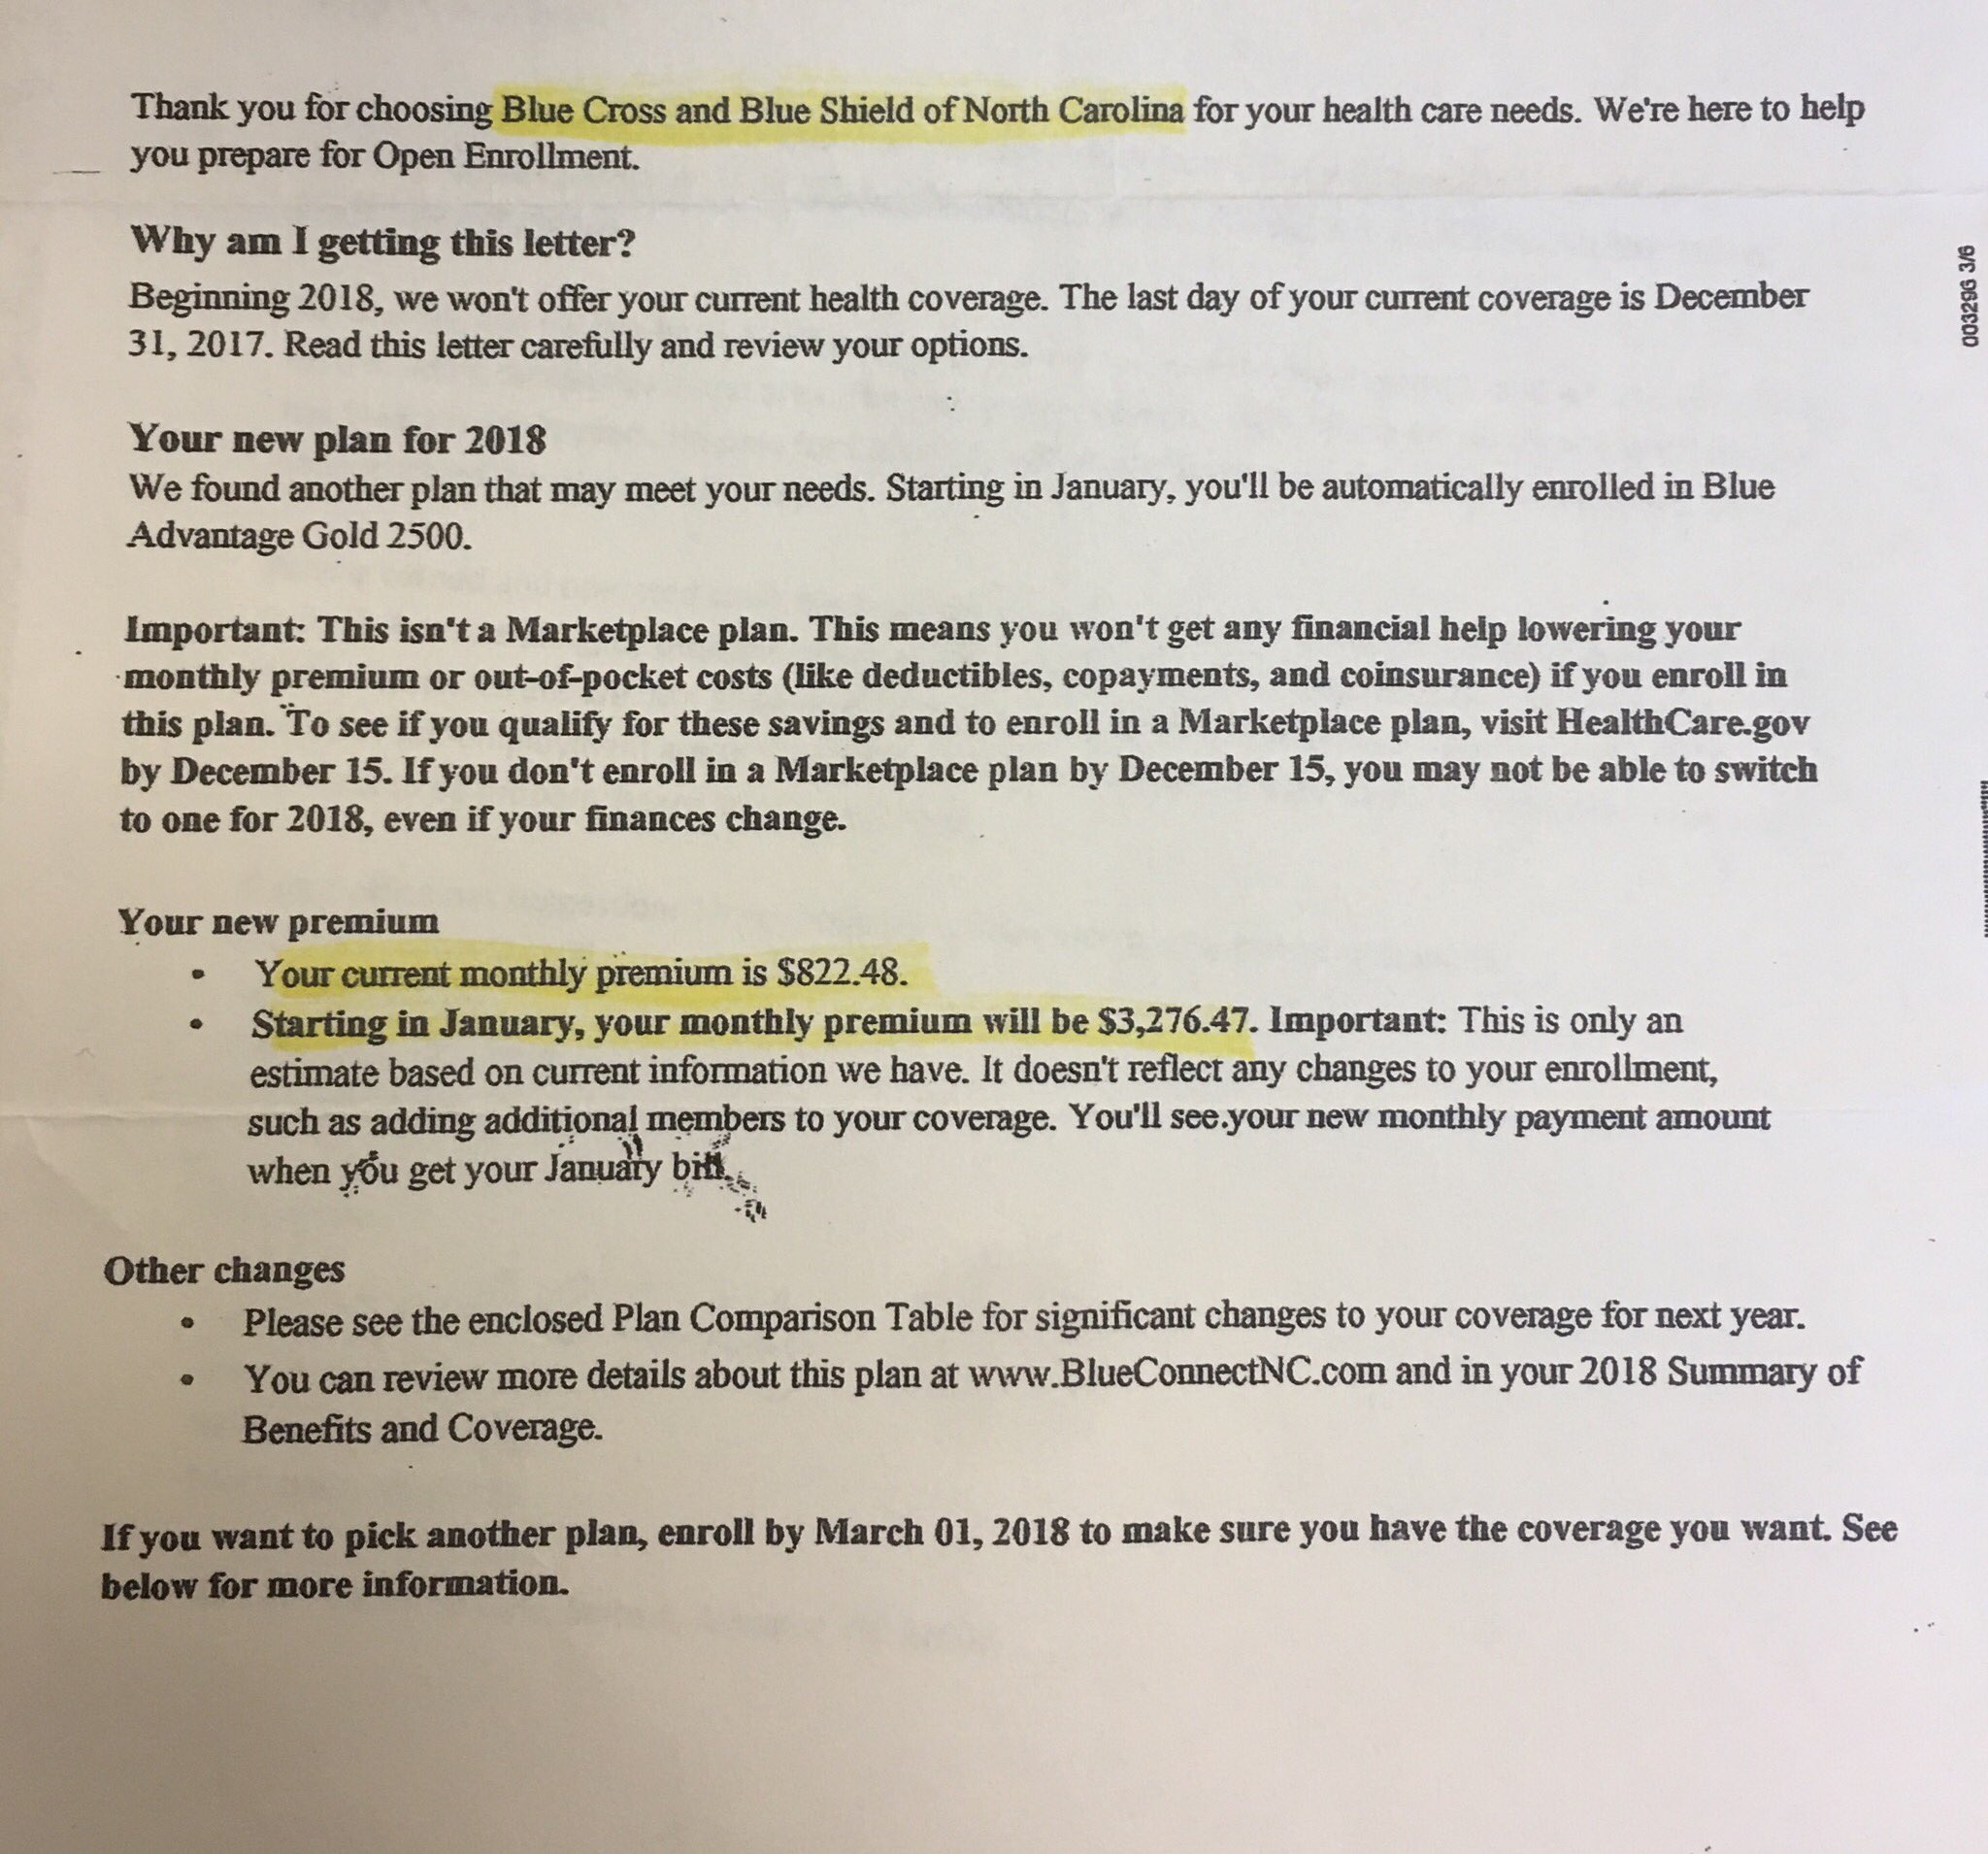
Tuesday evening a buddy of mine sent me a text regarding insurance for his employee. Since it's only two employees in his small business they don't offer a group plan. The text exchange below is why the middle class is getting crushed with Obamacare. It's also a huge reason why using a professional insurance agent can make a big difference.


Even with the huge subsidy they will still pay $5100 for a $12,500 deductible. That's 8.5% of their income in premium and an additional 21% of their income if they meet the deductible.

The Affordable Care Act. Well, maybe not so affordable.

Friday, November 24, 2017

Life Happens: Parent’s Sacrifice – and Gift

Roberto Loera spent his winters working at ski resorts in Colorado, and his summers in Mexico with his family. The time came that his family's visas had been approved, and they could be together year 'round.

Unfortunately, that wasn't destined to last; fortunately, he'd listened to his insurance agent:


[Hat Tip: Illinois Mutual]

Wednesday, November 22, 2017

The Positive Side of Sharing

We try not to take too firm a stand on products we don't sell, and of course a healthy skepticism is always in order for non-insurance products that claim to pay for health care.

For example, we've blogged quite few times on Health Care Sharing Ministries, most recently here:

"My claim from October had still not been paid. Yesterday I received a notice ... that since I was no longer a paying member my medical claims are no longer eligible for payment!"

But we also know folks who've had positive experiences. This past Spring, for example, long-time IB reader Thomas L reported that:

"We are using a sharing ministry, Samaritan Ministries, as of September.  In Oklahoma, the premium increase for this year was announced at 51% and all but BCBS were exiting the market statewide*.  This is after an almost 40% increase the year before."

Yikes.

But again, it's not just about saving money upfront: how will one fare once claims start to accrue?

Well, recently Tom sent this update:
"Baby is here!

So far so good on all things Samaritan.  All current expenses are already paid, the money for the obgyn is pre-paid to the clinic (which for whatever reason they hold in escrow), and the money for the hospital’s delivery estimate I have in a separate account ready to go, but since he was just delivered on 9/17, we have not had any bills yet.
I’ll have a much fuller report after the hospital really bills us, and, if it is like last time with BCBS, that weird never-ending stream of bills from the doctors and staff that come into your hospital room but technically aren’t with the hospital, so bill you separately."
Mazel tov!

Thanks, Tom, for keeping us updated, and have a GREAT Thanksgiving!

Tuesday, November 21, 2017

New News from the Herr Gruber Department

Thanks to our good friend Rich Weinstein, we have new video from Jonathan Gruber in the run-up to last year's elections:


Pull quote: "Not only is Obamacare a great law, and successful, but it was done so “honestly”

Click here for the full story...

Monday, November 20, 2017

Puzzling CHIP

Okay folks, what's missing from this?


[click to embiggen]

Hint: CHIP ain't free (and it's not "insurance").

Answer: 8.5 million kids covered ... at what cost?

These are children of families that "don't qualify for Medicaid, yet can't afford private insurance," which would would seem to be describing the "middle class," but apparently not.

And despite its name, CHIP is NOT insurance: there are no premiums, no skin in the game.

And here's a question: since we're required by law to buy health insurance that includes first dollar preventive care benefits, why aren't these kids on ObamaPlans? Surely it can't be for economic reasons: these plans are, after all affordable and effective.

'Tis a puzzler.

[Hat Tip: FoIB Bill M]

Friday, November 17, 2017

Some Thoughts on ObamaComp

Although I'm no longer actively working in this market, I do get the various carrier updates and contractual changes. Yesterday's mail brought this from Evolent (to which I'm connected via what used to be Premier Health Insurance):

"On behalf of Premier Health Plan, Evolent Health would like to thank you for your relationship ... it is necessary to amend [your contract]."

Regular readers already know where this is heading, but I think this may be instructive as to why I received a particular phone call yesterday:

 
[click to embiggen]

I would estimate that it takes at least a good hour (likely more, plus service time after the sale) to do a decent job for a client, even when there are so few choices still left. And of course, there's overhead and the like, so that $5 is quickly eaten up.

And once again I would ask: will their rates be lowered to reflect the decreased comp?

(Spoiler Alert: Not likely)

Oh, about that phone call?

Well, I was the third or fourth agent she'd contacted about health insurance for her son and daughter-in-law. They're currently with CareSource (which is primarily a Medicaid carrier, but has branched out into the "commercial" arena, as well). The county in which they live currently has these health insurance choices: CareSource. Since they don't use agents, there's no incentive for anyone to sell them. Which is why the poor lady was so frustrated.

And who can blame her?

Oh, did I mention the almost 100% rate decrease increase?

Insult and injury, ObamaCare is thy name.

Thursday, November 16, 2017

This Picture: What's Wrong With It?

NAILBA - the National Association of Independent Life Brokerage Agencies - is currently in the midst of its 36th annual convention, and by all accounts a fine time is being had by all. Which is, of course, great, but also provides an excellent illustration of the disconnect between trade groups such as this (and of course, they're far from unique in this regard) and how the public perceives those of us in the field.

Several years ago, I noted the irony inherent in a continuing education course on ethics:

"My fellow participants couldn't understand why I was giggling about an "Ethics" course given - for free! - to agents who'd received a "goody bag" full of tschochkes (chip clips, staplers, etc)."

Well, apparently the folks sponsoring that class were pikers:


ExamOne is a vendor agents and carriers use for medical exams for insurance applicants.

So much for those Ethics CE requirements....

Wednesday, November 15, 2017

Another Government-run Health Care Success Story

Words fail:

"A veteran committed suicide by setting himself on fire in front of a New Jersey VA clinic after staff at the clinic repeatedly failed to ensure he received adequate mental health care"

Charles Ingram, a 51 year old Gulf War vet, was actually cleared for treatment at a non-VA facility, but the bureauweenies in charge failed to follow through.

But sure, let's go all-in on state-run health "care."


[Hat Tip: FoIB NARNfan]

Tuesday, November 14, 2017

Sad news

We've just learned of the passing of Dr Uwe Reinhardt earlier today. His was a voice of reason and thoughtfulness, and he had a unique talent for making complex health care policy understandable.

We first noted the great work of Dr Reinhardt in this post by co-blogger Bob back in 2009:

"The insurance industry is congenitally weak in bargaining with supply side of the American health sector,” explained Princeton University health economist Uwe Reinhardt on a recent NPR Money Planet segment. Reinhardt believes that insurers largely dance to the fiscal tune whistled by hospitals and physicians."

A little over a year later, co-blogger Mike quoted another great example of Dr Reinhardt's insight:

"Thus, after blushing over miserly fee updates, taxpayers might go on to ask physicians why an average annual compound increase of 5.4 percent in spending per Medicare beneficiary was not enough to give the nation’s elderly good medical care."

Ouch.

He will be missed.

Monday, November 13, 2017

From the P&C Files: Foreign General Liability

Regular readers know our friends at Global Underwriters for their wide array of travel medical options, but they also work the other side of the insurance fence: since a lot of their business comes from employers with substantial international exposure, GU has an interesting product called Foreign General Liability (FGL) coverage. I'll let GU's Peter Schulteis explain:

"Today, thriving companies aren't just operating globally. They're sourcing, producing, recruiting, and genuinely "thinking" in global terms. However, most domestic General liability policies only cover lawsuits brought within US borders. This leaves US companies, schools, churches, non-profits, etc. and their international operations without a legal or financial safety net if taken to court abroad."

Okay, so what is Foreign General Liability coverage?

"FGL primarily consists of 3 main benefits:

■ International Commercial General Liability: The first line of defense against costly legal actions arising from events occurring outside US borders.

Typical Coverages: Bodily Injury and Property Damage, Employee Benefits Liability, Personal and Advertising Injury Liability, and Medical Payments.

■ Employer's Responsibility/Worker's Compensation: Outside the US, nothing quite compares to our nation's own worker's compensation system for comprehensive coverage [ed: as we've seen before].

Typical Coverages: Foreign Voluntary Worker's Compensation (Statutory worker's comp benefits for US and Non-US employee's), Employer's Liability - Bodily injury coverage to employee's for accident or endemic illness contracted outside the US.

■ Foreign Auto Liability: Each country and jurisdiction around the world has its own rules and regulations concerning automobile liability - from who would be at fault if an accident were to occur to how an automobile liability claim should be handled.

Typical Coverages: Applies to any auto of the insured, including owned, hired, and non-owned vehicles, Auto Bodily Injury/Property Damage Liability
."

Nice. What are typical coverage amounts?

"FGL limits are typically $1 - $2 Million, with the possibility of increasing benefit limits to $5 Million, if desired."

Thanks, Peter!

If you (or someone you know) would like additional details (or even a quote), be sure to stop by Global Underwriters'
site.

Friday, November 10, 2017

It's a Holly Jolly Friday LinkFest

(All links courtesy FoIB Holly R)

■ Britain's Much Vaunted National Health System© continues to prove that gummint-run health "care" #Fails at reining in costs:

"[T]hree highly influential health think-tanks - the King's Fund, the Nuffield Trust and the Health Foundation - published a joint report calling for an extra £4bn to be given to health next year."

Heh.

■ "Every Hour, Prostate Cancer Kills 45 Men. This Foundation Has Raised $769 Million to Fight it"

And yet, unlike mammograms, prostate exams aren't considered Essential Health Benefits (so they aren't first dollar).

Men's Health Matters (but not to ACA proponents).

■ And now for some good news:

"In world first, Israeli hospital employs MRI designed for infants"

MRI's have become almost as ubiquitous as X-Ray machines and EKG's, but one of the challenges is that patients need to stay very still while being scanned, which is a problem when dealing with infants. The generally accepted solution seems to have been anesthesia, but that poses its own set of risks in ones so small and vulnerable. This device seems to have solved the problem.

Yasher koach (that's Hebrew for "Kudos")!

Thursday, November 09, 2017

The ACA is Working - and Better than Expected!

Given that the explicit goal has always been single-payer:


[click to embiggen]

Health Wonk Review - Notable Quotables edition

Our good friend (and favorite health care economist) Jason Shafrin hosts this week's fun, uniquely designed roundup of health care fun and policy.

Wednesday, November 08, 2017

LifeAid: An Accelerated Benefits story

Back in the 80's and early 90's, when the AIDS "epidemic" was just taking off, a lot of folks - especially singles and the elderly - began looking for ways to leverage their life insurance policies. For those with no dependents, keeping a policy in force made little sense, and by selling their plans they could raise quick cash to pay for alternative treatments, or even just take a cruise.

Unfortunately, this lead to a lot of questionable practices, and even more questionable tax implications.  And so, as part of HIPAA, a new word entered the popular lexicon: viatical. Basically, one can sell one's plan to a 3rd party with little (or no) tax consequence.

Naturally, insurance companies weren't too keen on any of this, but the cat was already out of the metaphorical bag. Eventually, the industry settled on  the old "if you can't beat 'em, join 'em" strategy, and thus was born the Accelerated Benefit Rider. These enable the policyholder to "access" the face amount as a living benefit. Naturally, there are some caveats and potential tax implications, but it's a reasonably effective answer to the viatical issue.

Illinois Mutual has provided a helpful primer on how they work:


Thanks, IM!

Another few words on Open Enrollment

Building on yesterday morning's post, it bears repeating that even though I'm no longer active in the individual market, I still get calls, emails and referrals seeking my assistance. Since I'm loathe to just leave folks hanging, here's a brief recap of what we usually discuss:

First, going bare is not necessarily an irrational decision. When one is facing thousands (often tens of thousands) of dollars in out-of-pocket before a plan kicks in, well, it's difficult not to at least consider this route.

Second, of course, is an ObamaPlan (although these have become increasingly difficult to find, since so many areas have only one or two available). These satisfy the ObamaTax, and cover pre-existing conditions.

Third would be Short Term Medical plans, which don't satisfy the mandate, but offer lower premiums and out-of-pockets.

Fourth would be Health Care Sharing Ministries, which are ACA-compliant, but pose their own challenges.

And finally, there's what I call "Dave's Plan," which is not ACA-compliant, but can offer a valuable bridge at a reasonable price.

And yes, I know: DPC is also an option,but I'm not going there until there's a cat plan available to wrap it.

Did I miss any?

Tuesday, November 07, 2017

Oy Canada: CanuckCare© Strikes Again

Previously on CanuckCare© Today:

"[A] doctor can not only deny life-saving treatment for a person in their right mind who wants it, but actually have that patient, against the patient’s will and with their full mental faculties, outright executed by lethal injection."

And that's if the patient is "fortunate" enough to even get an appointment.

For many, that's quite the luxury:

"I actually thought I misread it’: Doctor ‘stunned’ over years-long wait for specialist appointment"

What the heck's she talking about?

Oh:


The joys of government-run health "care."

But hey: it's free!

[Hat Tip: FoIB Dr Gerard G]

Back in the (MMO) Saddle Again

As regular readers know, I've basically called a moratorium on new individual health insurance sales. At least part of that is driven by the fact that my immediate service area offers exactly 3 carrier options, none of which I'm interested in representing (let alone selling).

But just a few miles north of here, Medical Mutual of Ohio still maintains a footprint, and I received a call from a young lady who was interested in climbing aboard the MMO bandwagon.

She's currently with Anthem, which is going away at the end of December (so much for that explicit promise). Fortunately for her, MMO offers a plan that fits her needs and budget, and is available off-Exchange (she's not subsidy-eligible, so no reason to venture into that dark cavern). I popped over the the MMO agent portal, ran the quote, and about 15 minutes later had her all signed up.

So why did I agree to write this case?

Well, for one, thing, it killed me to leave this poor lady hanging: she knew enough to avoid the online marketing sharks, and had educated herself on what she really needed. In short, exactly the kind of client I prefer.

So, sometimes the exception makes the rule.