Tuesday, June 09, 2015

ObamaTax Breakage

There's an old saying in retail: You break it, you bought it. One most often encounters this in, for example, fine china shops. Notice, though, the construction: if you break it, then you buy it.

On the other hand, I've never understood why, since no Republican voted for (or supported) the ACA, they are in any way obligated to offer any alternative. And yet, the press (and even members of the party) insist that there's some kind of obligation to "replace" it with some other (no doubt cobbled together) plan.

This is akin to saying "well, a rival of yours broke it, now you must pay for it."

Rubbish.

And it appears that I'm not alone in this calculation:

"No Republicans voted for Obamacare, so it’s not their problem to fix."

So opines David Harsanyi, writing at the National Review. David's expertise in this area goes back a long time, which adds credibility (as if it's needed) to his argument:

"Most [Republicans], in fact, cautioned that passing the largest health-care reform in American history — written by one party, jammed through using reconciliation, and haphazardly implemented — could be problematic as not only an ideological matter but a practical one. Now they have to act?"

Spot on.

Of course, we don't call it The Stupid Party© without reason, so expect to see a spate of articles like this one (from Employee Benefit Advisor):

"House Republicans [have] introduced a plan to repeal the Affordable Care Act and replace key pieces of it with high-risk health pools and tax credits that benefit industry experts oppose, saying it would undermine the employer-sponsored health care system in place today."

Leaving for a moment the relative merits of such a plan (and I do, in fact, think it's worth consideration), there are a number of problems with the formulation:

First, as noted above, Republicans are not obligated to put forth any plan, let alone a "replacement" one. And second, why is it a given that "employer sponsored" health plans are the bee's knees? As we've previously blogged, employers don't tell us what groceries or house to buy: they pay us our wages and we're free to make our own choices. Why should health insurance be any different?

Monday, June 08, 2015

Clear as mud

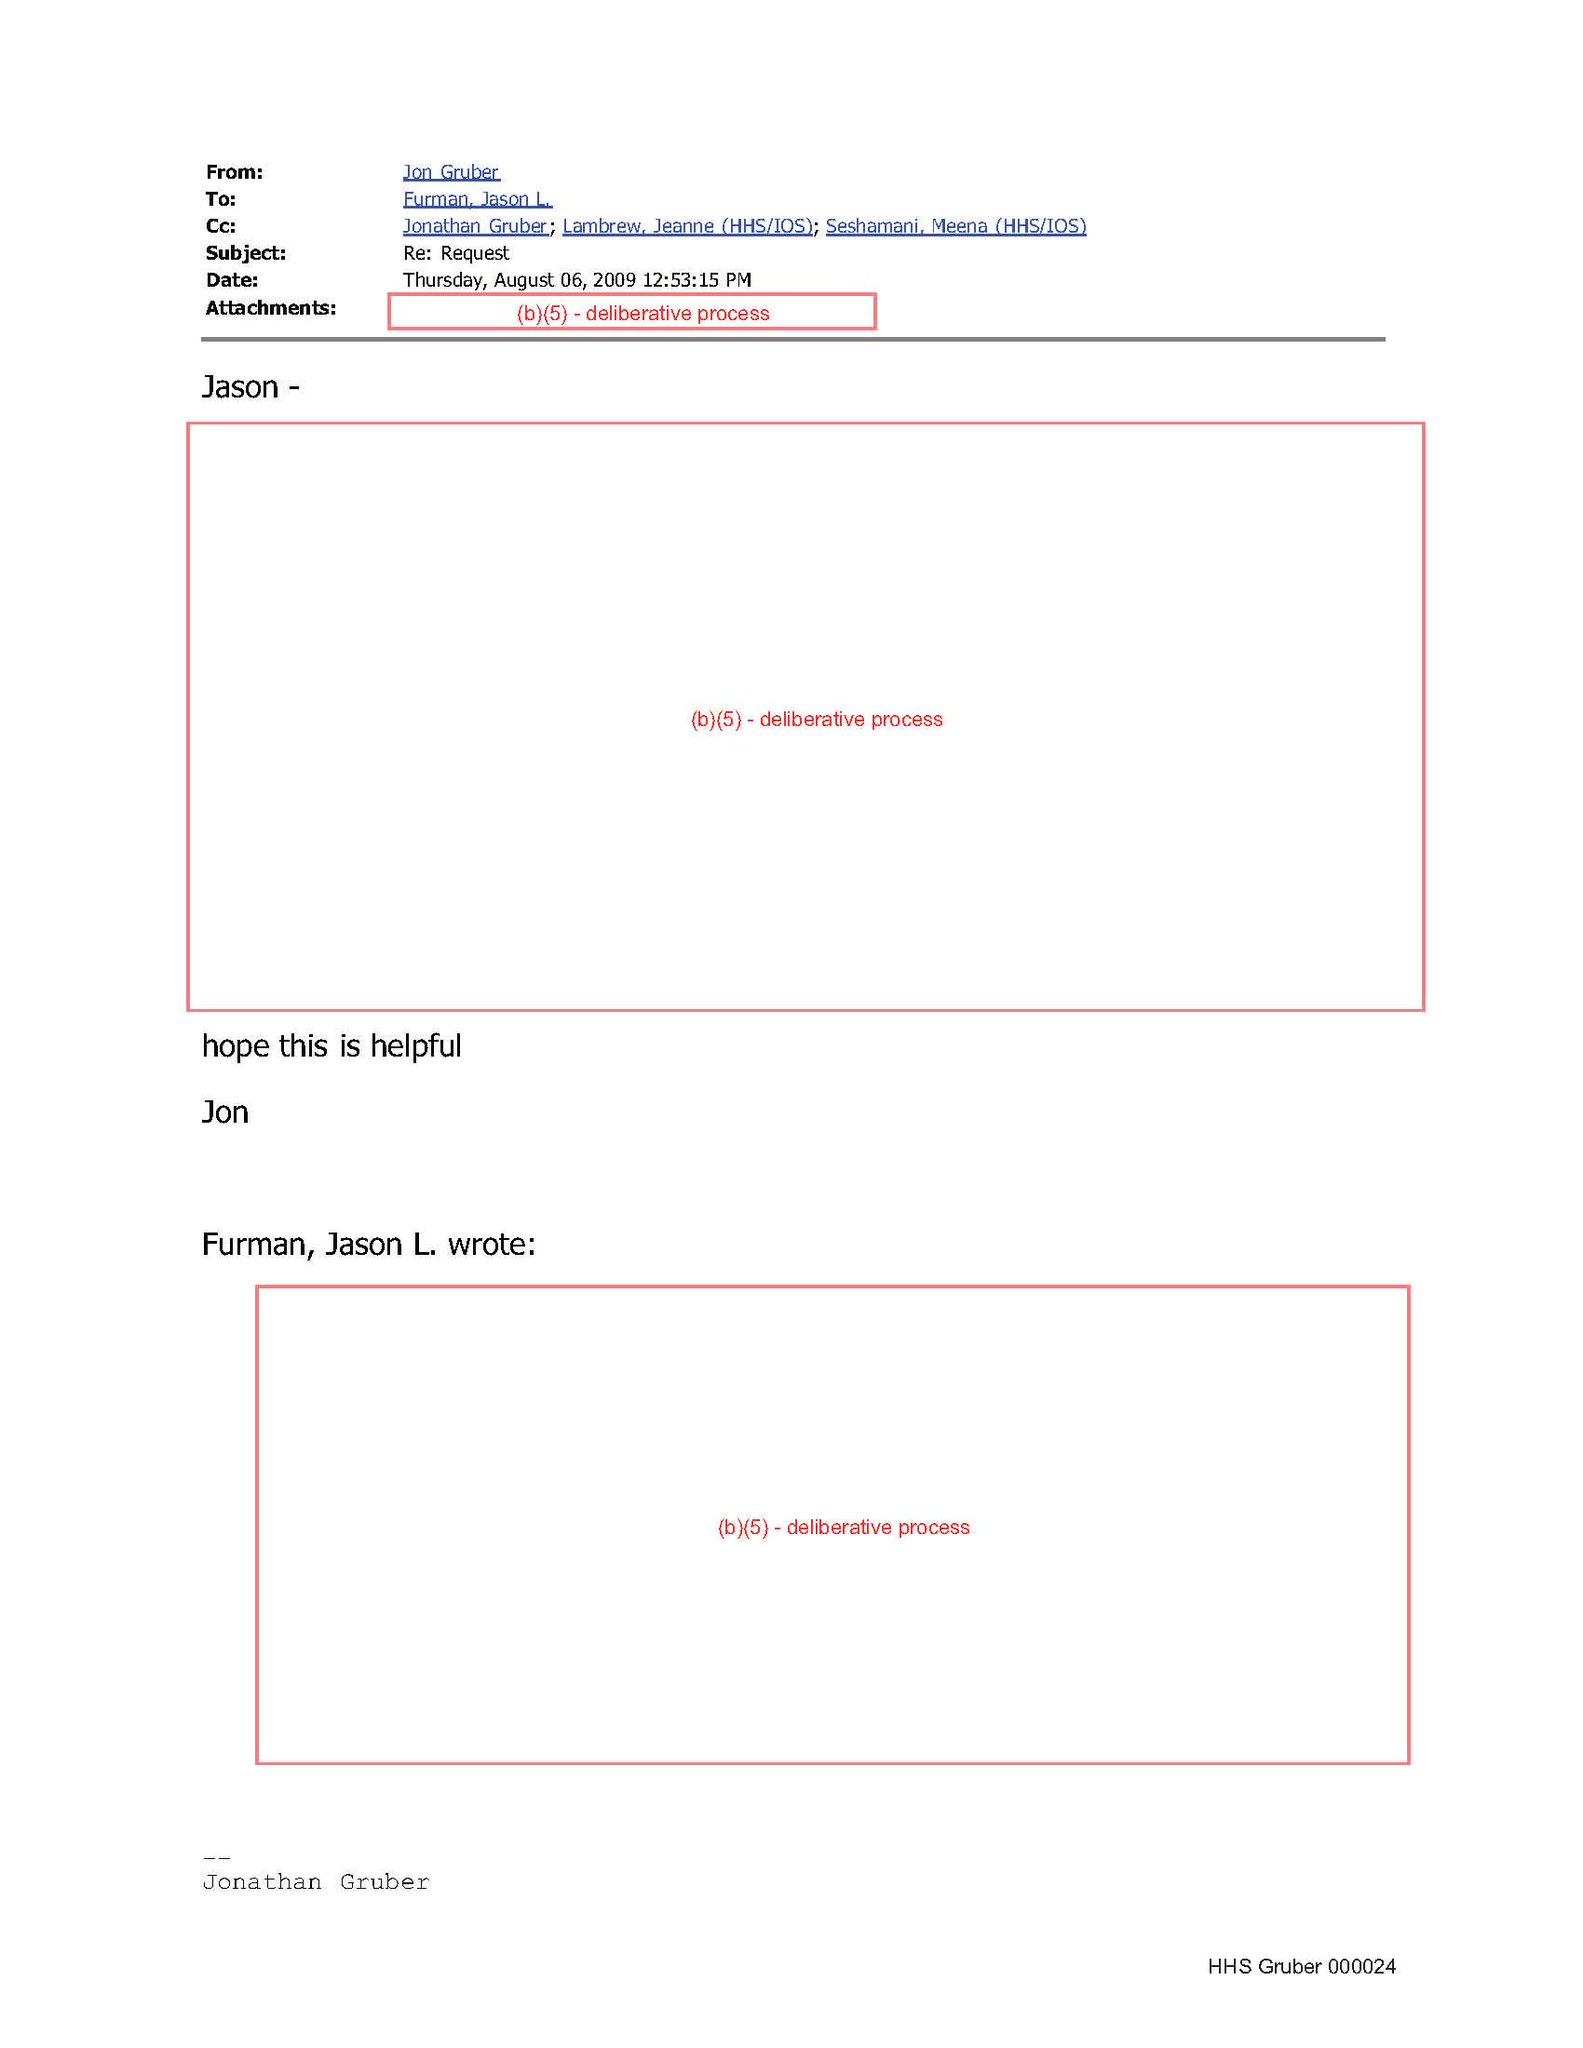
(via Twitter) Well. This clears that up. The Obamastration has released some 750 pages of emails and other doc's on Herr Gruber's role in drafting the ObamaTax.

Here's a sample for your edification:


Thursday, June 04, 2015

Thursday ObamaTax News (Oy)

■ First up, FoIB Jeff M tips us to this breaking news lie:

"Blue Cross and Blue Shield of North Carolina requested a 25.7 percent increase to premium rates ...  the N.C. Department of Insurance must approve the request ... apply only to ACA plans, meaning those purchased largely through the federally facilitated marketplace"

Why is this a lie? Because we were explicitly promised 3000% rate decreases.

Let's unpack this a bit farther: these plans affect only those bought On-Exchange, meaning that most (if not all) of them will be subsidized (why else risk the 404Care.gov security black hole?). Higher premiums mean higher subsidies, and thus higher taxes for the rest of us.

Gee, thanks!

On and, by the way?

In late-breaking "news," looks like most other Tar Heel State insureds will get to share in the joy noted above:

"Most state residents will see their health insurance costs rise next year under proposed pricing plans from insurers offering health coverage."

You're welcome!

■ Next up, Green Mountain State citizens may have dodged the aforementioned 404Care.gov bullet, but they'd be wrong:

"The online insurance marketplace that Vermont built to enroll people in private coverage under the law had extensive technical failures ...  even though its residents’ subsidies appear safe for now, Vermont stands as a cautionary tale."

As readers may recall, the current SCOTUS subsidy cases are about states (like North Carolina) that outsourced their marketplace efforts to the Feds. Since Vermont went the DIY route, their citizens' subsidies should be safe (for the nonce). Still, state leaders had hoped to springboard into single-payer, and now see those plans crumbling.

Gee, darn.

■ And finally (but by no means least): you know all those folks touting the recent "success" of Open Enrollment v2.0? You know, the one where they (allegedly) enrolled an additional 10 million suckers folks on ObamaPlans?

Well, aside from the fact that they repeatedly (and conveniently) fail to disclose how many of those folks had been previously insured and then lost their old plans, the results themselves are, in fact, a bitter disappointment:

"A little bit of math shows that sign-ups in 2015 came in 22% below the CBO's earlier forecast."

Ooops.

So it seems that - quelle surprise! - O'Care proponents not only moved the goalpoats, they also failed to score.

Oh well: lose some, lose some.

Health Wonk Review: Hello Summer!

Our good friend Louise Norris hosts this week's collection of interesting and thought-provoking posts on health care wonkery.

Come for Roy Poses fisking of the JEJM, stay for Jaan Siderow's excellent advice on planning for the future.

Wednesday, June 03, 2015

The Lighter Side of Health Care

Our own Kelley B has written about the new ICD-10 codes that providers use for billing purposes. Not everyone, though, is as up to speed as she is:


Tuesday, June 02, 2015

MVNHS© Doubles Down

It's been a while since we last checked in with Britain's Much Vaunted National Health System©, and it's, um ... heartening to see that they haven't lost their touch. On the one hand:

"Elderly people are being denied life-saving operations because of age discrimination within the [MVNHS©] ... New data reveal for the first time that across large areas of the country, almost no patients above the age of 75 are receiving surgery for breast cancer or routine operations"

Now, we were assured two years ago that the (infamous) Liverpool Pathway was no more. And yet, here we are:

"Last October, the Government introduced age discrimination laws which mean patients should not be denied procedures on grounds of age ... [but] Prof Norman Williams, said the scale of the differences was “extremely worrying,” raising suspicions that some parts of the NHS were operating covert blanket bans against procedures on age grounds."

That is, while the practice is technically illegal, it is at least tacitly  approved for use by the rocket surgeons who provide care to seasoned citizens. On the other hand, maybe seniors just need to pony up a bit of coin:

"Hospitals are letting patients jump NHS queues for knee and hip replacement surgery if they pay for the operations themselves."

Actually, this isn't exactly breaking any new ground. Early last year, we reported on the case of Grandma Stanton, an elderly subject of the Crown, who was denied life-saving chemo and was forced to sell her house to pay for it. She would probably have appreciated knowing that simply greasing the correct palms might have saved her home - and her life.

As it is, "[p]atients are being charged up to £14,000 for some procedures – almost treble the cost to the Health Service – leading to accusations that hospitals are ripping off the sick." So the Brit's do, in fact, have in place a tiered health care system favoring those with the cash to pay for that care. In fact, there's quite the little cottage industry amongst the various MVNHS© "trusts" (hospitals) to attract such patients:

"[M]ore than 40 trusts are promising patients they can have the ops in as little as a week – if they can afford it."

Seems like a promising candidate for GroupOn, no?

Monday, June 01, 2015

Monday Morning Spindle-clearing

In no particular order:

■ Our thoughts and prayers go out to the Biden family on the loss of Beau to brain cancer. The fight against this terrible disease is still on-going, but help may soon be on the way to save other families from experiencing this kind of loss:

"MD Anderson researchers identify protein with therapeutic potential for brain cancer ...  FGL2 protein is a crucial immune-suppressive factor in glioblastoma multiforme (GBM) cancer. As such, blocking FGL2 may promote GBM patients’ enhanced survival."

Still early days, but promising.

■ Courtesy of FoIB Holly R, we learn that "44% of Covered California customers report difficulty paying premiums." Of course, this must be a lie, since the President explicitly promised that rates would decrease by 3000%.

So there.

■ Regular readers know that part of that Medical Loss Ratios are a grab-bag of admin costs which carriers must use to determine whether or not they're paying out enough in claims. One controversial such expense has been agent compensation (fees and/or commissions). The Center for Consumer Information & Insurance Oversight (CCIIO) has recently clarified when that comp may not be excluded from carriers' MLR calculations (Spoiler Alert: pretty much always). Look for lower commissions and fewer agents (that's NOT a good thing, by the way).

Friday, May 29, 2015

The Flip Side of Halbig/King/Burntwell

The goal of The ObamaTax was to extend health insurance (and thus, presumably, health care) to the minority of Americans without it. It's been an article of faith that the subsidies are what will drive that goal. The Supreme Court has yet to rule on Halbig (etc), but that hasn't stopped the chattering class from opining on what a tragedy it will be if they strike down the government's (illegal) extension of subsidies to residents of states using the 404Care.gov Exchange.

But there's another side to this, one which has thus far gone unremarked: is there a potential upside to folks whose subsidies go away? Turns out, there likely is. In fact, the case for enforcing the law train-wreck as written is pretty strong:

"Nearly 8 million people currently enrolled in 37 states through the HealthCare.gov site would lose their health insurance [by] losing their subsidies. Premiums would spiral out of control as the only ones left in the exchanges would be the sickest and most expensive patients."

Okay, making the defendants' case, so what's that "flip-side?"

"[A] new report ... says that these critics are looking at only one side of the equation ... the claim [is] that 8 million will lose insurance assumes that everyone who loses subsidies in the federal exchange would cancel their health plans."

While it's likely that many - perhaps most - would, in fact, opt for the (toothless) penalty fine tax, it's by no means certain that all of these folks would bail. After all, as IBD points out, most of these folks were already paying for insurance before the ObamaTax. It seems reasonable, then, to presume that a good portion of them would suck it up and continue paying unsubsidized premiums.

But wait, there's more:

"[P]eople in [the affected] states would be eligible to enroll in low-cost catastrophic plans, something that they can't do now without also paying the individual mandate penalty."

This is key: many folks really just want/need catastrophic cover, without unnecessary (and expensive) bells-and-whistles.

As an aside, this would be a perfect opportunity to expand HSA eligibility to these types of plans. Hint, hint.

Perhaps the greatest benefit is the one least discussed:

"Getting rid of the subsidies has benefits, too: Namely, both the individual and employer mandates would get flushed away with them."

How's that, you ask?

Well, if getting rid of the subsidies renders coverage "unaffordable" (an ACA "term of art"), then the penalty no longer applies, thus saving consumers even more money. In fact, the "study finds that 11.1 million people will be free of the individual mandate, and more than a quarter million businesses will be liberated from the employer mandate" if the plaintiff prevails: "No subsidies, no mandate."

Four words I can get behind.

Oh, and the other upside?

That would be the north of 230,000 new jobs, plus higher pay for both full- and part-time workers.

So what's the rub?

Well, all of these goodies likely go away if the rocket surgeons in Congress decide to "fix" the ObamaTax instead of deleting it. What are the odds of that?

Thursday, May 28, 2015

A Quarter Trillion here, A Quarter Trillion there...

And pretty soon, you're talking real dollars:

"Obamacare is set to add more than a quarter-of-a-trillion—that's trillion—dollars in extra insurance administrative costs to the U.S. health-care system"

Keep in mind, these costs will be borne by insureds; that is, carriers will simply increase premiums to cover them. Remember: companies don't pay taxes or premiums.

And at "a whopping 22.5 percent of the total estimated $2.76 trillion in all federal government spending for the Affordable Care Act," it's just one more example of the way that the ObamaTax continues to hurt the very folks it was ostensibly passed to help.

BONUS: The rocket surgeons that wrote the report itself continue to buy into the long-since-debunked idea that Medicare "has overhead of just 2 percent." They then use this faulty "data" to justify the move to single-payer.

Of course.

[Hat Tip: Co-Blogger Bob]

Wednesday, May 27, 2015

Unfortunate Client Timing

Got  a call this morning from the daughter of one of our agency's long-time clients. In addition to his auto and home, my long-since-retired colleague had written a life insurance policy for him. As the official "Life/Health guy," it fell to me to get the ball rolling on the claim, so I called the carrier's home office to get that started.

The first question I always ask is "is the policy in force?" That is, is it still active and thus able to be paid out. The answer is almost always "yes," and then I start asking about beneficiaries, face amounts and the like.

So I was a bit startled when the customer service rep said "no, that policy was cancelled at the insured's request."

Whoa.

In fact, the cancellation request came in almost exactly a year ago. Of course, unless he was being treated for a terminal illness at the time, it seems unlikely that the insured knew that this was, perhaps, premature. I have no idea why he cancelled the plan; perhaps he had adequate coverage with another agent, or it had grown unaffordable, or some other reason. All I know is that it's now my sad duty to let his daughter know that there's going to be no payout from that policy.

'Tis a shame.

Potentially Stupid Customer Tricks [UPDATED]

[First posted @ 5-26-15. Please scroll down for Update]

We first blogged on the insurance issues associated with ride-sharing services (eg Uber, Lyft) back in 2011:

"Seeing a business opportunity in millions of cars that sit idle at office parking lots or on weekends, several start-up companies have introduced "peer-to-peer" car-sharing services ... Likewise, renting out your car to someone you've never met (and will probably never even see!) is a dramatic change in the nature of your insurance policy's risk."

Fast forward 4 years, and despite the success of these ventures, and the swelling population of drivers and fares customers, many of the same issues remain. In fact, the very first sentence of this post contains an egregious error: it ain't "ride sharing," which sounds more like car-pooling than what Uber, Lyft, et all actually comprise, which is ride selling (and buying).

These transportation networking companies (TNCs) are, for purposes of insurance, pretty much taxi (or livery) services, and your personal auto policy isn't designed (or priced) to reflect that. The TNCs may offer some protection through a corporate liability policy, but that may apply only when a driver is actively engaged in transporting a customer.

And that's just one of the many insurance challenges facing both drivers and passengers:
■ How much coverage is actually available when the driver does have a fare?
■ How will your insurer react if you have a claim?
■ What happens if you don't tell your agent?
And more. Unsurprisingly, I tend to fall in the "better safe than sorry" camp.

[Hat Tip: P&C Guru Bill M]


UPDATE: Home Office friend of mine sent me this:

"Just saw your post. We've been discussing this issue (Uber, etc); currently our view is that there are 3 stages of Uber: 1) you are listed as available, 2) you accept a pickup request, and 3) you pick up the customer and take him/her to the destination. If an accident occurs during #1, there is coverage. If an accident happens during #3, no coverage. During #2, very grey area."

Thanks! Color me (still) skeptical, though: seems to me that stages 1 and 3 still make one a taxi/livery service (else why advertise "availability?"). But hey, I'm a simple unfrozen caveman lawyer life and health guy.

Friday, May 22, 2015

Life Partners back in the news


In 2012, we noted that "Life Partners Holdings, Inc. has been cleared of allegations by Texas state securities officials that it did not register life settlement transactions as securities under state law."

So, bullet dodged, right?

Not so fast there, pardner:

"The bankruptcy trustee for Life Partners Holdings Inc. is seeking to control the proceeds of life insurance policies held by its customers after his own investigation revealed a number of new ways he said the company committed fraud."

Yeah, the ol' shock meter seems busted right now.

And my 5 year old prediction seems pretty much confirmed:

"Artificially shortened life-expectancy figures supplied by the company convinced investors that their returns would be greater ... [LP] charged massive undisclosed fees and misrepresented the company’s business practices."

And the list goes on.

Look for this to get even messier, and we'll keep you posted.

Thursday, May 21, 2015

Health Wonk Review at Julie's Place

HWR co-ordinator Julie Ferguson steps up to host this week's 'Review (your scheduled host, moi, is dealing with end-of-life issues with the canine member of our family).

Please drop by for some great insights.

Unalienable Insurance?

Via co-blogger Bob:

Wednesday, May 20, 2015

Dear HHS, Will You Share My ACA Success Story?


March 23, 2010 was an historic day for health insurance in America. It was on this day when we all rejoiced knowing that Obamacare was going to reduce the average premiums for a family of four by $2500. It was going to help small businesses find affordable options to offer employees. It was going to eliminate "junk" insurance policies. Employees were told that if they liked their plans they could keep them.
So how has this Obamacare thingy helped my small company:
  • We have seen an overall decrease in benefits since 2010.
  • From November 2010 to our current plan year premiums have increased 58.7%.
  • If we would have been forced to an Obamacare compliant plan the increase would have been 116.7%
Numbers don’t lie. Click on the picture to see the real impact.

Tuesday, May 19, 2015

Blue Grass State HIX Blues

So this happened:

"[T]he Kentucky Health Cooperative, an ObamaCare creation funded initially by federal dollars and then bailed out with tens of millions of dollars more last year, is insolvent."

Ooops. And of course, the bureauweenies behind this massive #fail appear to be circling the wagons. Which is not unexpected, but a shame, nonetheless.

And why is it a shame, you ask?

Well:

"The Kentucky Hospital Association outlined its concerns in a report released Friday called “Code Blue,” saying payment cuts to hospitals are expected to reach nearly $7 billion through 2024. “Kentucky hospitals will lose more money under the Affordable Care Act than they gain in revenue from expanded coverage

It's almost as if the system itself is imploding. The bigger question, of course, is whether this is by happenstance or design.

You be the judge.

Another 1,000 Words on O'Care

Courtesy FoIB Jeff M:


Monday, May 18, 2015

(Not So) Shocking O'Care news

Last week, we reported on the latest Volunteer State health insurance premium woes:

"BlueCross BlueShield of Tennessee has filed to increase its health insurance premiums for 2016 individual plans by 36 percent, on top of a 19 percent increase approved last year"

Never fear, though, 5 other states are next in line:

"[E]xchange insurers in six states where 2016 rate requests have already been filed are seeking to raise rates an average 18.6% next year."

That 36% hike in Tennessee was the high water mark this time 'round; Beaver State carriers are seeking a more modest 24% increase. Folks in Connecticut get a break, with average rates increasing just shy of 8%.

Now, there are some that would argue that this is to be expected, and can't be totally the fault of The ObamaTax.

These folks would be wrong, it is 100% attributable to the train-wreck:

Thursday, May 14, 2015

Gender Bender Preventive Care

So, the kind folks at Ballard Spahr (a well-known benefits law firm) passed along info on the efforts by Our Betters in DC© to more stringently enforce the so-called Preventive Care requirements in ObamaPlans. There's the usual litany of "free" (cf: TAANSTAFL) items, and then this particular turn of phrase caught my eye:

"In applying preventive service recommendations that are sex-specific to particular individuals (for example, a transgender individual)"

Regular readers know that the exhaustive list of preventive care requirements contain exactly ZERO male-specific benefits. So here's a conundrum: folks undergoing female-to-male "transitioning" will be giving up valuable coverage, with no corresponding decrease in premium.

Is this fair?

When can we expect to see the first lawsuit?

Will there be popcorn?

Cover Cali sputtering

As Bob pointed out last month, The Golden State's health exchange (Covered California) continues to burn through tax-payer dollars at an alarming rate. That wouldn't necessarily be a bad thing if, say, they had something - anything, really - to show for it.

But alas:

"After using most of $1 billion in federal start-up money, California's Obamacare exchange is preparing to go on a diet"

And why is that?

Well, it's actually pretty simple:

"[A] reduced forecast calling for 2016 enrollment of fewer than 1.5 million people."

You'll recall, of course, that the primary purpose of The ObamaTax was to increase the roles of the insured. Adding insult to injury, that pesky first 'A' in PPACA continues to remain out of reach, even with subsidies:

"[H]ealth policy experts said that some uninsured folks still find health insurance unaffordable"

The problem, of course, is that folks who qualify for subsidies still find it difficult to come up with the scratch to cover mega out-of-pocket maximums, and that's when they're successful even finding a provider who takes ObamaPlans.

So, the state is tightening its metaphorical belt:
• Spend $58 million less compared with the current fiscal year, a 15% reduction.

• Devote the largest portion, $121.5 million, to outreach, sales and marketing. That's down 33% from the current year.

• Maintain the monthly $13.95 fee for each individual policyholder, which would raise $233.2 million in revenue.
I find #2 to be the most ludicrous: sell all you want, if folks can't afford what you're selling, well...

So, who's next?